MarketsHigh
Dangote Cement Passes ₦20 Trillion. What Does That Mean?
A 10% single-day jump took Dangote Cement past ₦20 trillion and the NGX to a record. We set out what happened, what the numbers show, where sources disagree and what comes next.
By Betini Udom Published 5 min read Editorial Policy Report a correction
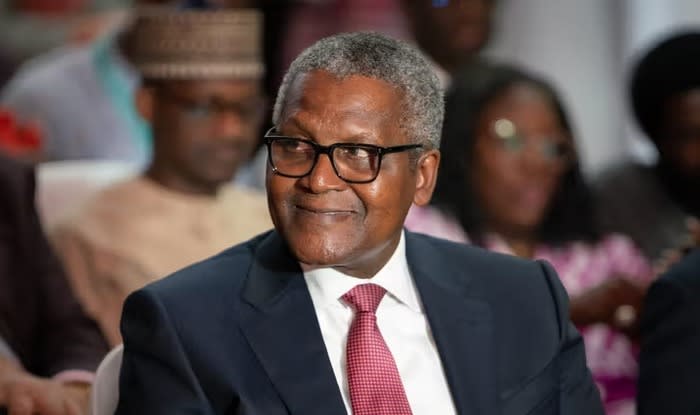
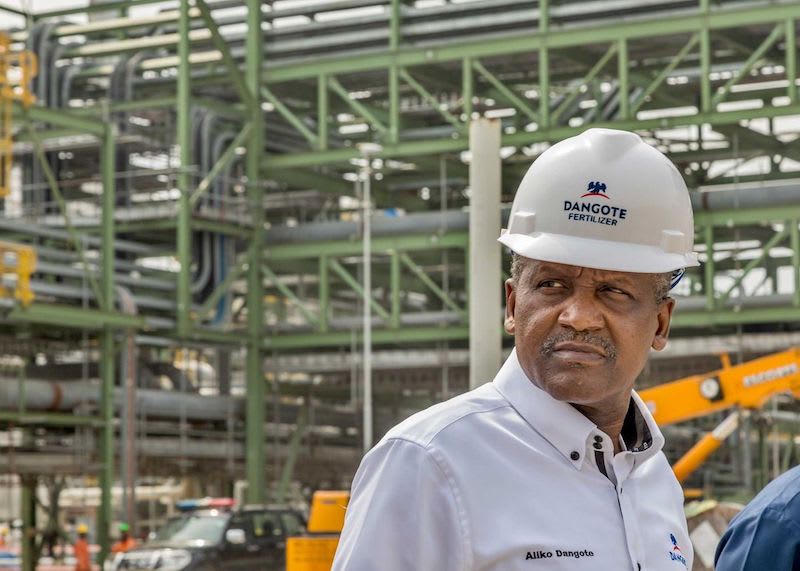
On Monday 26 October 2026, shares in Dangote Cement rose about 10%, from ₦1,111 to ₦1,222.10. The company's market value went from ₦18.5 trillion on Friday to ₦20.6 trillion, the first close above ₦20 trillion. It is the second most valuable company on the Nigerian Exchange (NGX).
Forbes's real-time ranking showed Aliko Dangote's wealth at $53.2 billion, up $1.2 billion on the day and from $51 billion on 20 October. The whole exchange was worth about ₦163.2 trillion, its highest in roughly a month, and the All-Share Index closed at 251,290.54, up from 247,222.30.
In Simple Terms
A share price multiplied by the number of shares gives a company's market value. When the price jumped 10%, the value of the whole company jumped by the same proportion. Dangote owns most of the cement company, so his wealth, which Forbes calculates from what he holds, rose too. Nothing changed in the factories on Monday; what changed was the price investors were willing to pay.
The Money
| Item | Figure |
|---|---|
| Share price, 26 October | ₦1,222.10 (+10%) |
| Market value | ₦20.6trn (about $15.7bn at ₦1,312 per dollar) |
| Share of the exchange | About 12.6% |
| Year-to-date share gain | 100.7% from ₦609 |
| Dangote's wealth | $53.2bn (Forbes live tracker) |
| Wealth a week earlier | $51bn |
| Refinery offer | 4.1bn shares at ₦525, about ₦2.15trn |
Dollar figures use the ₦525-to-$0.40 rate implied by the refinery's offer price and are approximate.
The Numbers
Cement results, six months to June 2026
- Revenue ₦2.51 trillion, up 21.35%
- Gross profit ₦1.59 trillion, up 30.51%; gross margin about 63.2%
- Profit before tax ₦981.39 billion, up 34.43%
- Profit after tax ₦638.53 billion, up 22.69%
- Earnings per share ₦38.22, up 24.33%
- Sales volume 14.94 million tonnes, up 11.79%
- Cash ₦796.28 billion, up 100.29% from December; financial liabilities ₦646.17 billion, down 44.28%
- Finance costs ₦112.11 billion, down 48.14%; net foreign-exchange loss ₦45.03 billion
The Nigeria business produced ₦1.81 trillion of revenue, up 25.17%, with a margin on earnings before interest, tax, depreciation and amortisation near 60%. The wider African operations produced ₦775.35 billion, up 13.67%, at about 17.6%.
Valuation. Doubling the half-year earnings per share gives ₦76.44. At ₦1,222.10 the shares trade at about 16 times that. This is a rough Rainingmoney estimate, not a forecast. Profit grew about 23% while the share price roughly doubled, so most of the year's gain reflects a higher multiple, not faster earnings.
Follow the Money
The cement link. The day's rise added about ₦2.1 trillion, around $1.6 billion, to Dangote Cement's value. His fortune rose $1.2 billion, which implies he owns something like three-quarters of that gain. This is our inference; Forbes does not publish its workings.
The refinery link. Forbes had him at $28.5 billion on 1 March, then at more than $51 billion by mid-September, after a reported private placement of about $2.5 billion in the refinery. The company is not listed, so what it is worth is an estimate. Pre-offer valuations circulated from about ₦77.7 trillion to ₦82.6 trillion, with another report citing unnamed people at close to $50 billion. They cannot all be correct.
The offer. Dangote Petroleum Refinery and Petrochemicals is selling about 4.1 billion shares at ₦525, roughly 3% of the company, to raise around ₦2.15 trillion ($1.6 billion). The window was extended from 13 October to 27 October, with the stated reason that investors across more African markets needed time to take part. Mr Dangote has said applications are three to four times the amount offered. The refinery's capacity is 650,000 barrels a day, with a plan to expand to 1.4 million.
Other investors. Reports that Femi Otedola, chairman of First HoldCo, is considering raising his stake in Dangote Cement to as much as 5% have not been independently confirmed.
The Bigger Picture
Concentration. At 12.6% of the exchange, one stock now steers the index. Monday's index gain was 1.65% while its heaviest member gained 10%.
Market context. CSL Research ascribes the market's resilience to strong earnings, improving macroeconomic conditions and policy reforms. It lists geopolitical tension, inflation, pre-election uncertainty and tighter global financial conditions as the risks.
Fact versus estimate. The share price, market value, half-year results and offer terms are published figures. The fortune is an estimate, the refinery's value a judgement, and the multiple our arithmetic.
The African angle. The refinery offer is designed for investors across several African markets, with depositary receipts already available in Kenya and Botswana and talks under way elsewhere.
The Jargon
- Market capitalisation: share price times number of shares; what the market says the company is worth.
- Price-to-earnings (P/E): share price divided by profit per share; how many years of profit you pay for.
- Re-rating: a rise in the multiple investors will pay, with no change in profit.
- Oversubscription: more applications than shares on offer, so each applicant receives less.
- Allotment: the process of deciding who receives shares.
- Gross margin: the share of sales left after production costs.
What Happens Next
Known. The refinery offer closes today, 27 October. Allotment proposals go to the SEC around 10 November, sign-off is expected around 17 November, and trading is pencilled in for roughly 8 December.
Possible. Cement could pull back after a 10% day; refinery demand could translate into a strong first-day listing; further revaluations could lift or cut the fortune.
Unknown. How the refinery will trade once public, whether cement margins hold near 63%, and whether the index can advance without Dangote Cement.
Rainingmoney's Take
This section is Rainingmoney's reading.
The ₦20 trillion mark is a milestone, but it is as much a story about price as about performance. The company is earning more and borrowing less, and that is real. Yet the shares now carry a premium that January did not, and a 10% day is the kind of move that can reverse. For readers, the practical question is how much of any gain comes from profit and how much from a changing mood. On the refinery, expect fewer shares than you apply for, and treat every valuation until trading begins as a guess.
Sources & Verification
- Source: BusinessDay · Dangote Cement H1 2026 results · Refinery IPO extension · Forbes figures, September
- Editorial note: This explainer is an original RainingMoney adaption of the report, RainingMoney has added explanatory context.
Founder and Editor-in-ChiefAbuja
Betini Udom
Founder and Editor-in-Chief of RainingMoney. Covers Nigerian, pan-African and global markets, finance and economic policy.
Author profile & archive →The Money Print
Market intelligence before the market opens.
Pan-African capital flows and the stories behind the numbers, on weekday mornings.